Tonight's Budget didn't just change tax rates. It changed the architecture of wealth accumulation in Australia.
Three reforms. One structural shift.Negative gearing quarantined. The 50% CGT discount replaced. A 30% minimum tax on discretionary trusts.
Full analysis below — including what changed, what didn't, the key dates you need to know, and what the full Budget Paper reveals that
the headlines missed.Read More…
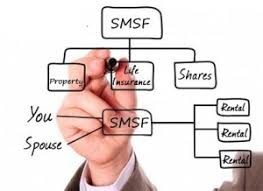
If you’re considering using your self-managed super fund (SMSF) to buy property, you’ll need the right structure in place.
One of the main ways to do this is through a Limited Recourse Borrowing Arrangement (LRBA).
Read More…
Australia’s passion for self-managed super funds (SMSFs) is stronger than ever. According to the ATO’s June 2025
quarterly statistical report,
SMSFs have officially surpassed the $1 trillion mark in assets, cementing their place as a key driver of retirement wealth.
Read More…
With over $4 trillion in superannuation savings, it’s no surprise that scammers see super as an easy target. The Australian
Securities and Investments Commission (ASIC) has issued warnings about the growing number of high-pressure sales tactics and
misleading promises
designed to trick Australians into risky superannuation switches. Since your super is likely to be one of your largest lifetime investments,
knowing how to protect it is essential.
Read More…
Superannuation is one of the most tax-effective ways to save for retirement. But the government sets strict annual limits,
called contribution caps, on how much you can add to your super. If you go over these caps, you may face extra tax.
Here’s what happens, your options, and how to avoid breaching the limits.
Read More…
If you’re aged between 67 and 75 and want to claim a tax deduction for personal super contributions,
special rules apply. You’ll need to meet the work test (or in some cases, the one-off work test exemption). Understanding
these requirements is essential to maximise your retirement savings and stay compliant with ATO rules.
Read More…
Many Australians hold life insurance and disability cover inside their superannuation fund. It’s a simple and
cost-effective way to get protection, but as retirement approaches, many people start to question whether it’s worth keeping.
There’s no universal answer. Whether you should keep or cancel insurance in super depends on your stage of life, financial situation, and
family needs. Here are the key things to consider before making changes.
Read More…
Thinking about an SMSF? Here's what most people get wrong. Control, flexibility, direct property... SMSFs sound like the ideal setup — but
they’re not for everyone.
If you’ve been wondering whether an SMSF is right for you, we’ve broken down the key things to consider.
Read More…
From 1 July 2025, the superannuation guarantee (SG) rate will increase to 12%, meaning
more employer contributions to your super fund. This change will boost your retirement savings over time but timing matters when it comes to
how much super you receive.
Read More…
If you're a healthcare professional focused on building a strong retirement strategy, it's important to stay up to date with the latest
changes to superannuation. From 1 July 2025, some key thresholds remain unchanged—while one important cap is increasing, offering new
opportunities for tax-effective retirement planning.
Read More…
As the 2025 financial year unfolds, understanding the nuances of superannuation and Self-Managed Super Funds (SMSFs) is paramount for
Australian businesses and high-income professionals. Proactive planning can help you maximise your retirement savings, ensure compliance,
and avoid potential pitfalls.
Read More…
Has your super balance taken a hit due to recent market fluctuations? While this might seem like a setback, it could actually open the door
to opportunities that weren’t previously available. In fact, now might be the perfect time to reassess your retirement strategy and make the
most of your super.
Read More…
Many people assume their superannuation will automatically go to their loved ones when they pass away. Unfortunately, that’s not always the
case. Unlike other assets covered by a will, your superannuation is handled separately. To ensure it goes to the right people, you need a Binding
Death Benefit Nomination (BDBN).
Read More…
If you have extra cash, you might be wondering whether to make additional concessional contributions to your super fund or use the money to
pay down your mortgage, whether it’s on your home or a holiday property. Both options have benefits, but the right choice depends on your
financial situation and goals. Let’s explore both strategies.
Read More…
Since its introduction in 2018, billions of dollars have been contributed through the downsizer superannuation scheme. This option is widely
used, yet three common misconceptions prevent even more people from taking advantage of it.
Read More…
Superannuation regulations are constantly evolving, and 2025 will introduce several updates that may influence your retirement savings.
Whether you are beginning to build your super or preparing for retirement, staying informed about these changes can help you make
well-informed financial decisions. Here’s what to expect:
Read More…
Superannuation and Financial Hardship: A Safety Net in Difficult Times
Superannuation is generally regarded as a long-term savings plan for retirement. However, in times of financial hardship, it can also serve
as a vital source of support. While super is primarily designed to fund retirement, there are specific circumstances where early access is
permitted to help individuals facing financial difficulties. This article outlines these provisions and how superannuation may provide
relief in challenging situations.
Read More…
Did you know that approximately 60% of Australians aged 67 and over receive the Age Pension? However, not everyone qualifies for the full
amount. This is because Centrelink assesses your wealth based on your income and assets, and if either exceeds certain limits, your pension
is reduced.
Read More…
Self-managed superannuation funds (SMSFs) and super wrap accounts are popular alternatives to retail and industry super funds for
individuals seeking greater control over their investments and potentially lower fees.
Read More…
The recent spate of cases before Australian courts and tribunals has highlighted questions around the Superannuation Guarantee Charge (SGC)
payments: specifically, when a payer might be responsible for SGC contributions for services rendered.
Read More…
Many SMSF trustees wonder if they can sell or transfer assets from their fund to a related party, such as themselves or a family member.
While regulations restrict certain asset purchases from related parties, there is no rule preventing an SMSF from selling or transferring
its assets, like property or shares, to a fund member or a related party under certain conditions.
Read More…
Superannuation laws have become more flexible in recent years, making it easier for older Australians to add to their superannuation later
in life. Here’s a summary of the key points about making super contributions.
Read More…
All superannuation funds aim to provide retirement benefits, but there are key differences between Self-Managed Super Funds (SMSFs) and
other super funds. It's important to compare it with other options before deciding.
Read More…
An SMSF (Self-Managed Super Fund) can be established by almost anyone, with a maximum of six members. Typically, SMSFs are set up by
individuals or couples, but other arrangements, such as involving family members or business partners, are also common.
Read More…
Since 1 July 2024, the age at which individuals can access their superannuation increased to age 60. So what does this mean for those
planning on accessing their superannuation upon reaching this age?
Read More…
Splitting superannuation contributions to your spouse can be a great way to boost your combined superannuation balances which can benefit
you both in retirement.
Read More…
A recent decision by the Full Federal Court around a man’s tragic death by suicide clarified the standing of a de facto spouse in the
context of a non- lapsing death benefit nomination on a life insurance policy made by the deceased person.
Read More…
Building an Investment Property? Split the Loan Before You Sign
Negative gearing for residential investment property is now limited to new builds. Why setting up separate land and construction loan facilities before you sign can protect a valuable interest deduction.
Practice Owners: Choose Your Trust Structure for the Sale, Not the Announcement
The draft trust rules offer an election with no restructure and no stamp duty \u2014 but the same percentages apply to capital. What doctors with practices in a family trust need to weigh up before choosing between the election and the roll-over.
The 30% Minimum Tax on Family Trusts: What Doctors Need to Know
Treasury has released draft law for a minimum 30% tax on family trust income from 1 July 2028. Here is what it says, what is excluded, the two ways out, and what doctors with trusts should do now.